Blog · 26 September 2026 · 3 min read
Water Damage Insurance Claim in Portugal: A Step-by-Step Guide
Short answer: stop the water, document everything with photos, report the incident to your insurer quickly, and get a written report from the plumber stating where the leak was, what caused it and what was repaired. Most multi-risk home policies in Portugal (seguro multirriscos habitação) cover sudden water damage, and a clear cause is what moves the claim forward.
This is general guidance. Policies differ — always check your own conditions, exclusions and excess (franquia).
What home insurance usually covers
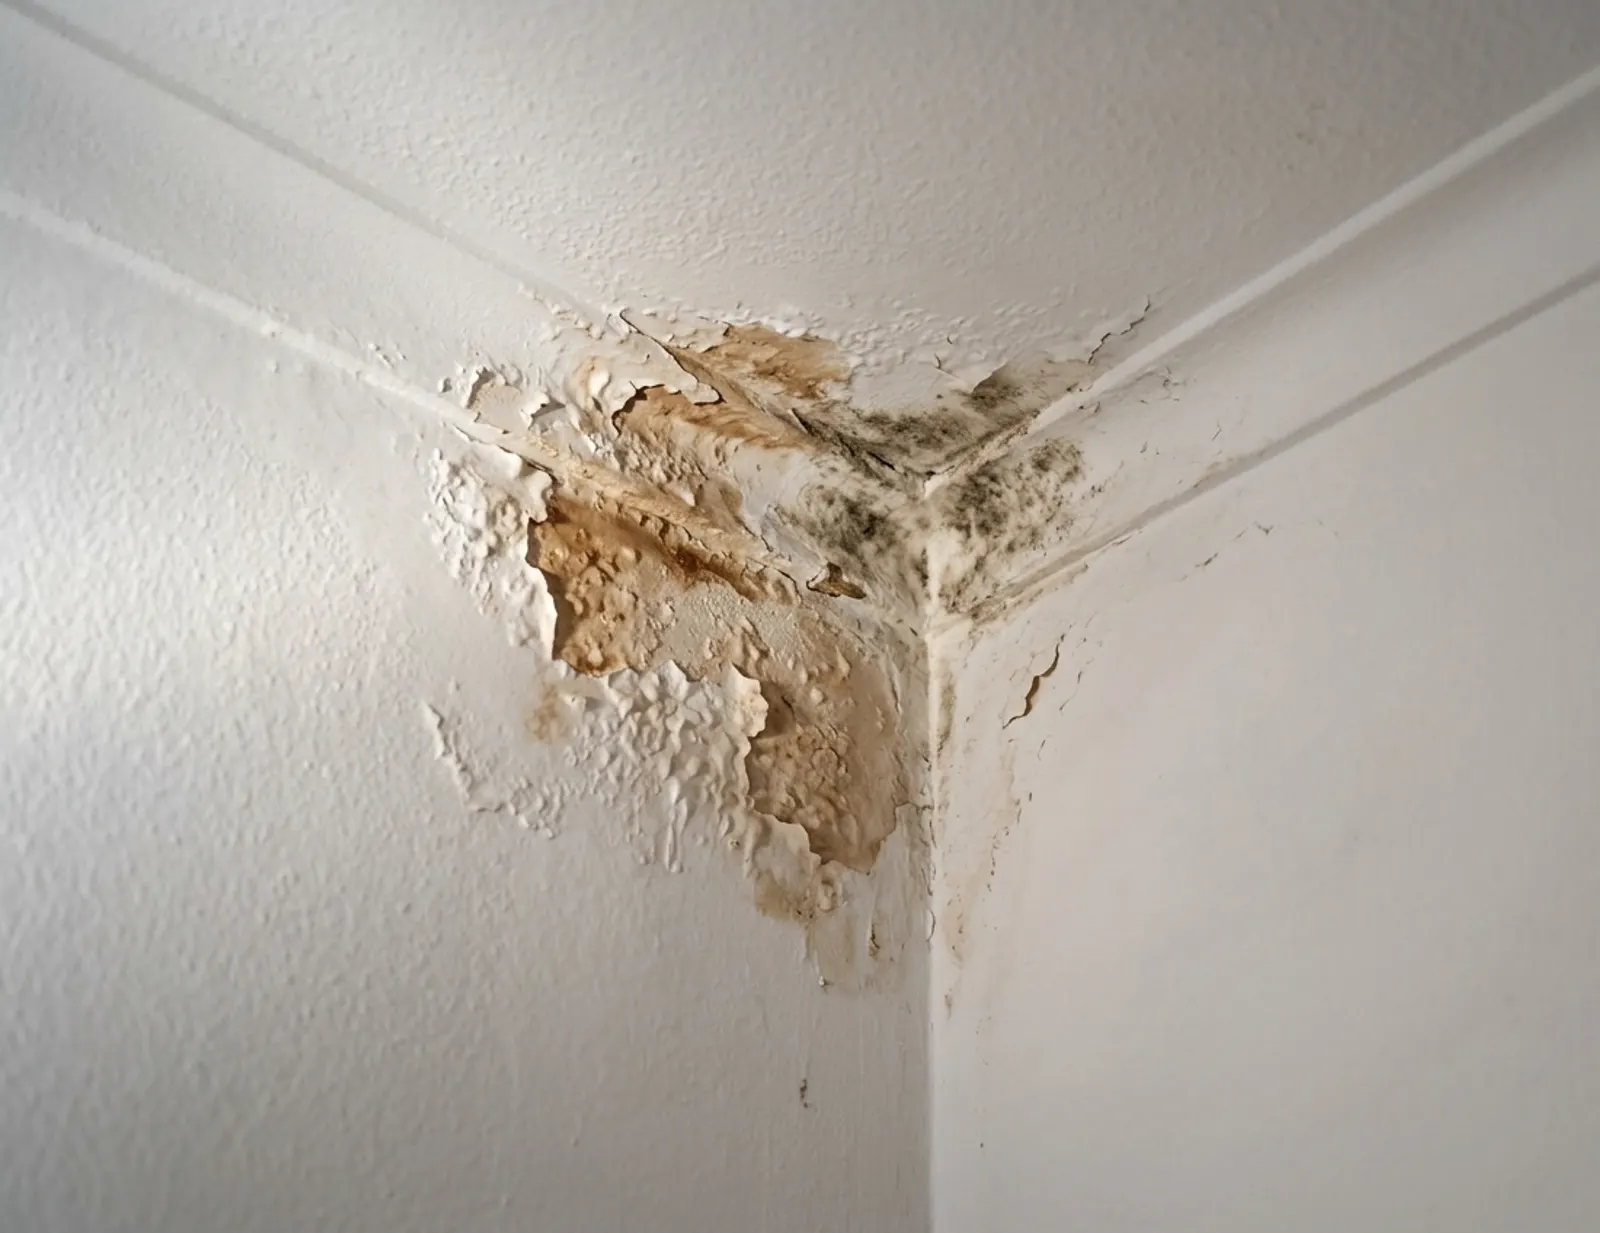
Damage caused by sudden water escape — a burst pipe, a failed hose, an appliance leak, water from the flat above. Many policies include civil liability for damage you cause to neighbours, and some cover the cost of locating the leak.
The building structure is usually insured by the owner or the condominium; your belongings by your contents insurance. Tenants often have contents cover only.
What is often excluded
Gradual damage from long-term leaks the owner should have noticed, wear and tear, lack of maintenance (a pipe known to be rotten for years), and condensation. The repair of the pipe itself is sometimes excluded even when the damage is covered.
That is why reporting quickly, and a professional report stating that the leak was sudden or hidden, matters.
Step 1: stop the water and make it safe
Close the main valve, switch off electricity near the water and limit the damage. Insurers expect you to take reasonable steps to prevent further damage. See burst pipe: what to do.
Step 2: document everything
Photos and videos before cleaning: the leak, the source if visible, the damage to walls, ceilings, floors and belongings. Keep damaged items if possible until the insurer says otherwise.
Write down dates and times: when you noticed it, when you stopped it, who you contacted.
Step 3: report to the insurer
Contact your insurer (or broker) as soon as possible — policies set a deadline for reporting. Describe what happened, send the photos and ask what they need.
If a neighbour was affected, exchange insurer details. If the source is in a shared pipe, inform the building administrator, whose building insurance may be involved.
Step 4: the plumber's report
Insurers want to know the cause. A written report stating where the leak was, what failed, whether it was hidden, and what was repaired — with photos — answers the questions that most often stall claims.
Keep the invoice for the leak detection and repair. See reports for insurers.
Step 5: the assessor visit
For larger claims the insurer sends an assessor (perito). Do not repaint or rebuild before they have seen the damage unless they authorise it. Have your photos, invoices and report ready.
Why claims stall — and how to avoid it
No clear cause. Late reporting. Damage repaired before the insurer saw it. Disagreement between neighbours about the source. A professional report and early documentation prevent most of these.
A checklist of documents
Your policy number and conditions. Photos and videos of the damage and the source. The plumber's report and invoice (leak detection and repair). Receipts or proof of value for damaged belongings. Contact details and insurer of the other party, if a neighbour or the condominium is involved.
Keep everything in one folder or email thread — it saves time at every step.
Neighbours and the condominium
When the leak affects another flat, each insurer usually deals with its own customer's damage and then settles with the other. You only need to report to your own insurer and share details.
When the source is a common part, the building's insurance is involved; the administrator reports the claim.
Preventing the next claim
Replace old flexible hoses, service the water heater, reseal the shower when the silicone starts to fail, and know where your main valve is. Many claims come from small parts that were visibly worn for months.
If you need the cause documented, leak detection starts from 120 € and includes a written report.
Your insurer wants to know the cause? We locate the leak and write the report — location, cause, repair and photos.
Leak reports for insurersFrequently asked questions
Does home insurance cover the cost of finding the leak?
Some policies do, some do not. Check your conditions or ask your insurer before booking.
I rent. Whose insurance claims?
The owner's insurance for the property; yours for your belongings, if you have contents cover.
Should I get the repair done before the insurer approves?
Stop the water and make it safe immediately. For the final repairs, follow the insurer's instructions.
What is the franquia?
The excess — the part of each claim you pay yourself, set in your policy.
Can you send the report straight to the insurer?
Yes — we can send it to you, your insurer or the building administrator, with the photos and invoice.
Services Lisbon plumbing team
Guides written by the plumbers who do this work in Lisbon homes every week — drains, leaks, water heaters and pipework.